
Just 1% of companies account for 80% of all business spending on OpenAI and Anthropic, according to corporate card giant Ramp, which tracks payments across more than 70,000 U.S. businesses. Ramp lead economist Ara Kharazian, who flagged the figure in early September, noted that spending on the two AI labs is more concentrated than in any other software category the firm tracks.
Per capita, the biggest spenders are overwhelmingly venture-backed. According to Ramp's summer report, the median VC-backed startup spent $76 per employee per month on AI - more than ten times the $7 spent at private equity-backed firms.
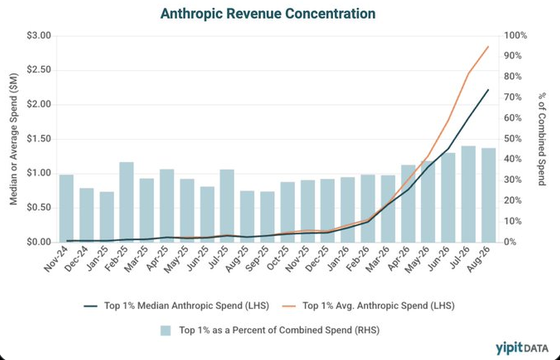
That top-heavy dynamic mirrors what YipitData uncovered at Anthropic specifically: the lab's top 1% of customers generated 46% of its revenue in August, nearly doubling from 25% a year earlier. How many of those whale customers, we asked at the time, are funded by the very same VCs backing Anthropic?
Anthropic's IPO prospectus - the updated version of which we dissected yesterday - confirms the concentration at the very top: just two unnamed customers generated nearly a quarter of its 2025 revenue, according to Reuters. Their identities aren't hard to guess. Last year, two AI coding tools - Cursor and Microsoft's GitHub Copilot - drove roughly $1.2 billion of Anthropic's $5 billion annualized revenue run-rate, as VentureBeat reported.
Follow the money. Cursor's parent company, Anysphere, raised $2.3 billion at a $29.3 billion valuation last November in a round co-led by Accel and Coatue, alongside Thrive Capital, Andreessen Horowitz, Nvidia, and Google. Three months later, Coatue and Singapore's GIC led Anthropic's massive $30 billion Series G, with Nvidia again participating. Coatue's cash flows into Cursor, Cursor spends it on Claude tokens, those tokens book as Anthropic revenue, and that revenue underwrites the markups on Coatue's Anthropic stake.
Even the scorekeeper is inside the loop. Ramp itself raised $1.85 billion at a $60 billion valuation last week in a round led by Dragoneer, Thrive, Founders Fund, Sands Capital, and Avenir Growth. Its cap table also features Coatue, D1, ICONIQ, GIC, Fidelity, T. Rowe Price, General Catalyst, and Lightspeed - every single one of which, alongside Dragoneer and Founders Fund, backed Anthropic's Series G.
Volumes Up, Dollars Flat
Yet it is Ramp's own economist who is documenting the cracks in the facade. In his October AI Index - pointedly titled "Cracks in the AI Thesis Part 3" - Kharazian reported that the top 1% of AI-spending firms shelled out $9,568 per employee in September. While that was up 11.7% from August, it remained 3.1% below July's peak of $9,873.
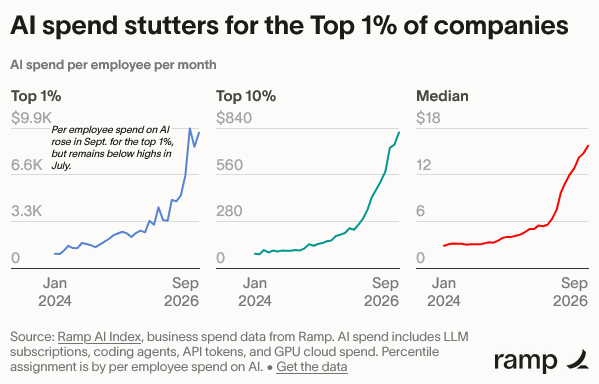
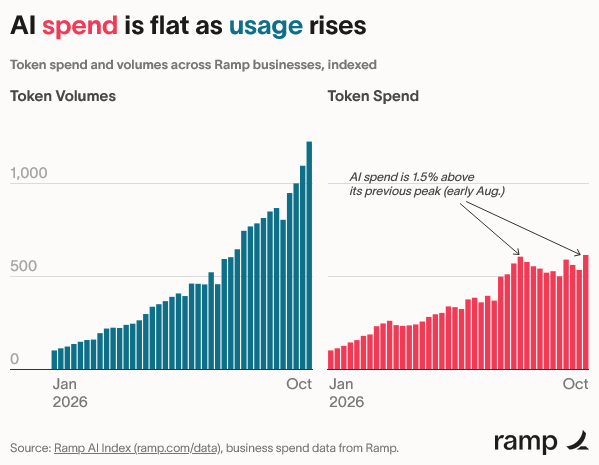
Across the broader cohort, the stall is even starker. In August and September, Ramp recorded "two straight months of virtually no growth in token spend," even as raw token volumes continued to climb.
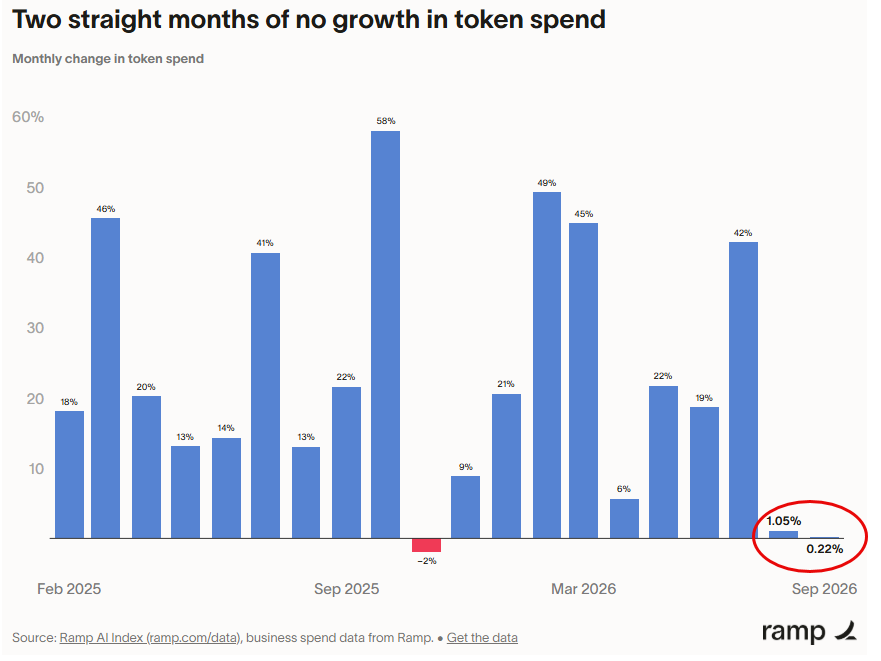
Total dollar spend did eke out a new high in early October, but cleared its previous August peak by a paltry 1.5%.
Source: Ramp Rate
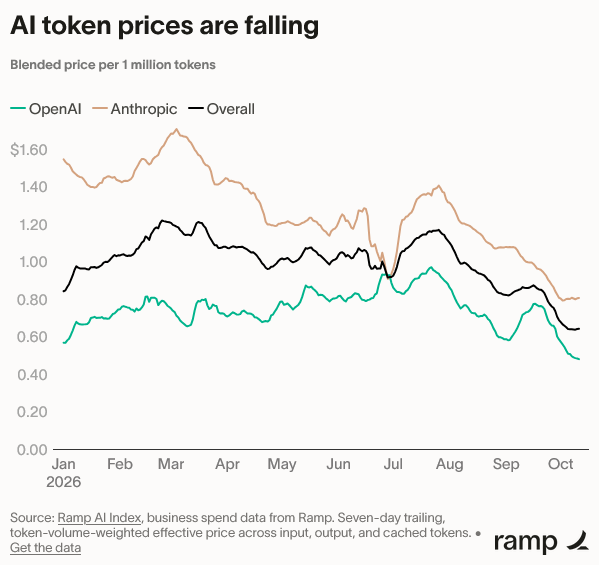
The culprit, according to Kharazian, is deflation: "the main driver is price declines at the frontier, in addition to efficiency and quality improvements for models across intelligence levels, that are driving the blended price per million tokens down."
Source: Ramp Rate
Nor have the AI labs been able to lock in their biggest customers. Asked whether OpenAI and Anthropic are using enterprise contracts to guarantee revenue, Kharazian noted that buyers hold all the leverage. Enterprise deals are rarely signed on the assumption of higher-than-normal spend, and when they are, "the labs are willing to provide concessions in the form of discounts on models from the sticker price." His takeaway: "These contracts could contribute to price cuts without driving additional volume."
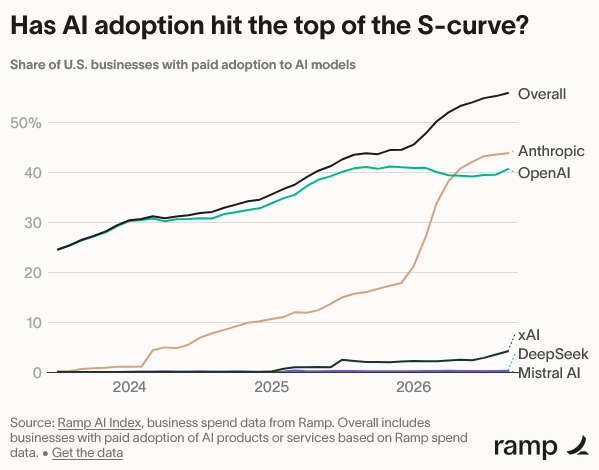
The customer base isn't widening much, either. Paid AI adoption across Ramp's corporate network nudged up just 0.62 percentage points to 55.9% in September. "It feels like we're at the top of the S-curve," Kharazian wrote, "where the growth in the market will have to come from more intense adoption rather than more customers."
Source: Ramp Rate
Anthropic Joins The Price War
Meanwhile, Anthropic's realized token price has been cut in half in just a month. The Ornn Anthropic Token Price Index - which measures the actual dollars customers pay per token consumed - has cratered to $0.83 per million tokens from over $1.70 in mid-September, marking a record low since the benchmark launched in June.
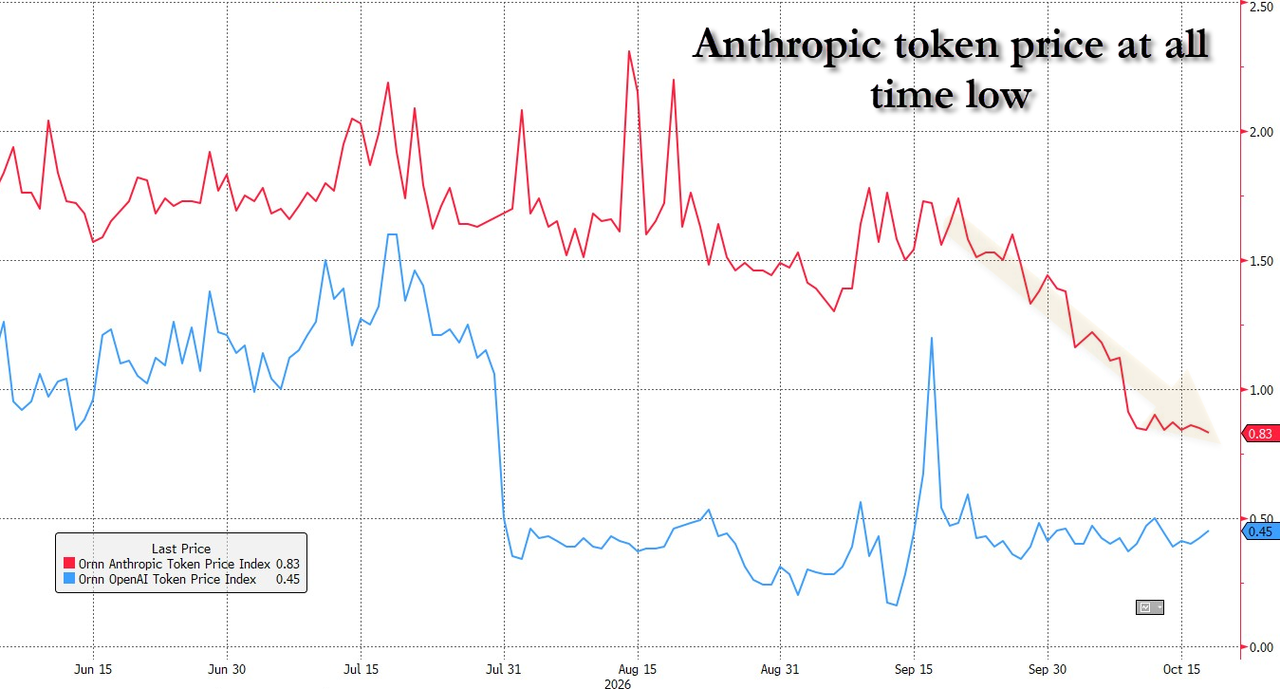
Even after that plunge, Anthropic remains pricier than OpenAI, whose index sits at $0.45. OpenAI's realized pricing collapsed in late July after it slashed rates on its GPT-5.6 Luna and Terra models by up to 80% - just three days after Chinese lab Moonshot released the open weights for Kimi K3, the model blamed for sending chip stocks into a bear market earlier that month. OpenAI has since reportedly leaned toward delaying its IPO until 2027.
Jevons Isn't Riding To The Rescue
The bulls' reflex answer to relentless price cuts is Jevons paradox: make tokens cheap enough, and usage will explode so fast that total revenue rises anyway. The data isn't cooperating. In a Sept. 25 note, Goldman Sachs warned that "token demand growth will need to outpace declining token prices to support continued growth in investment spending," noting that while "frontier models are currently a key source of demand for hyperscaler compute," cheap open-source rivals are rapidly gaining ground. By Goldman's estimate - built on Anera and OpenRouter data - total token demand has surged roughly 18-fold since December, but demand for high-margin frontier models has grown only half as fast.
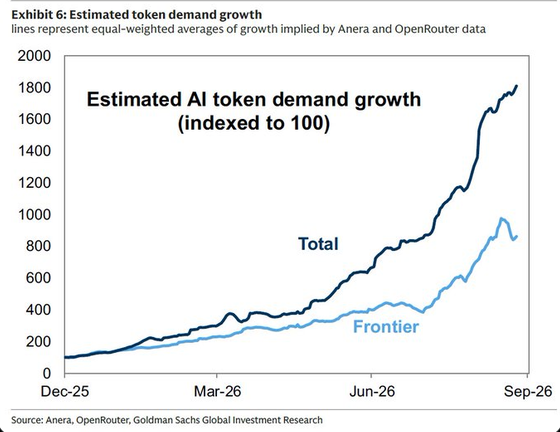
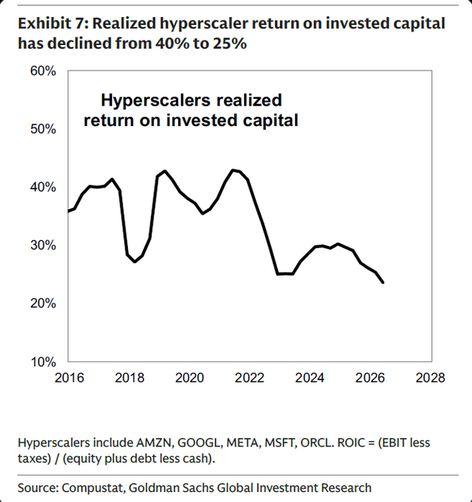
That margin squeeze is now flowing directly upstream to the companies building the data centers. Goldman calculates that realized return on invested capital (ROIC) across Amazon, Alphabet, Meta, Microsoft, and Oracle has fallen from 40% to 25% - the lowest reading in its dataset going back to 2016.
On Tuesday - the same day Citadel's Ken Griffin told Bloomberg that markets are "almost certainly" in an AI bubble - Apollo chief economist Torsten Slok diagnosed the underlying demand problem. "Silicon Valley operates on the premise that compute demand is unlimited, yet the recent slowdown in token spending growth suggests that this appetite may exist only when compute is effectively free," Slok wrote, citing Ramp's figures. Instead of inelastic hunger, compute faces "a flat, highly price-sensitive demand curve, where even modest changes in token prices can drive buyers to throttle usage or substitute cheap open-source alternatives."
"Ultimately, the number-one variable governing the viability of data center construction models is not physical capacity or power; it is the actual price users are willing to pay for the compute being built," Slok concluded. Corporate buyers will only pay a premium if they can translate tokens into "higher top-line growth, bigger profit margins or substantial cost savings, little of which is showing up at scale yet. Maybe that will come in the future. Maybe not."
Back in June, Ramp product director Adam Sommer boasted to a New York panel that "our largest AI spenders at Ramp are seeing their spend double month-over-month for the last several months." Three months later, the top 1% were spending less per employee than they had in July.